
The appraisal industry is transitioning to a redesigned appraisal report, known as the new Uniform Residential Appraisal Report (URAR), which is built on the Uniform Appraisal Dataset version 3.6 (UAD 3.6). This mandated change is directed by the U.S. Federal Housing Finance Agency (FHFA). PAR talked with Michelle Czekalski Bradley, a real estate broker, certified general appraiser and USPAP instructor, to answer some questions Realtors® need to know. You can watch a PAR webinar highlighting these changes as well.
What appraisal changes?
Fannie Mae and Freddie Mac (the GSEs) are replacing the legacy appraisal forms, which have been largely unchanged since 2005, with a single, dynamic, data-driven appraisal report that is generated through appraisal software and adapts to the property type.
When do changes take place?
Some appraisers and lenders started limited use of the new reporting system last year (September 2025), and the report has been broadly available since earlier this year (January 2026). Use of the new appraisal report becomes mandatory on Nov. 2, 2026, for all new Fannie Mae and Freddie Mac appraisals.
It’s important to note that if you have a transaction beginning in September, you might want to ensure that the appraiser is using the new reporting system. The deadline is based on the date the appraisal is submitted to Fannie Mae or Freddie Mac, not the date the loan application was taken. Once the Nov. 2 deadline hits, any appraisal submitted to the GSEs must use the new reporting system.
Will this apply to every sale?
It applies to conventional loans on 1-4 unit residential properties that are sold to Fannie Mae or Freddie Mac, which are the majority of mortgages. FHA has announced it is adopting the new report, with optional use beginning in 2026 and a mandatory date still to be announced; VA and USDA have not yet released timelines. It does not apply to portfolio loans a bank keeps in-house, commercial transactions or cash sales.
Will appraisals take longer?
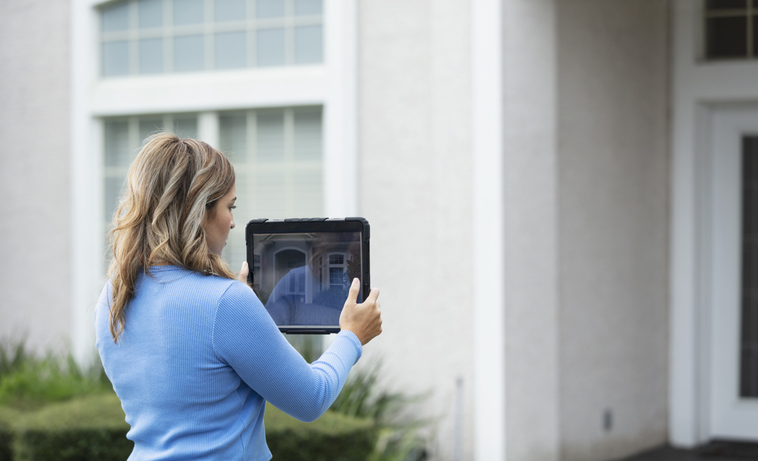
Yes. The new reporting system requires appraisers to collect more measurements, photos and data points, and many appraisers will now enter that information onsite using a tablet or phone, rather than back at their office. Real estate agents should plan to build a longer appointment into expectations and prepare their sellers for this.
Will turnaround times be affected?
Probably, especially through the transition as appraisers learn the new system and its requirements. Everyone involved, including appraisers, lenders and appraisal management companies, is adjusting to the new process. Building extra time into contract dates may be helpful initially.
What’s different about the new report?
Almost everything. A summary is provided to make key findings easier to locate. You’ll notice photos will be more prominent in sections and information is in a different order.
Kitchens and bathrooms will now be classified according to new criteria. Getting accurate information about the property from your sellers will be more important than ever.
Will the appraiser ask the seller (or agent) more questions?
Yes. Expect questions about what was updated in the home, when and with what materials, especially kitchens and baths, but also for items such as the roof, HVAC, windows and additions. Having these answers will help speed up the appointment and improve the accuracy of the report.
What can I do to prepare my seller for these new reports?
Explain that the appraisal will take longer and appraisers will photograph each room and that all areas need to be accessible, e.g. basements, attics, garages and outbuildings.
Have your seller document the property’s improvement history before the appraisal: what was done and approximately when. This information needs to be included in the new appraisal report.
What can listing agents do on the MLS side?
Accurate listing data matters more than ever. The new report captures property information at a much more detailed level, and appraisers will be comparing what they observe onsite against what the MLS says. Double-check your square footage, room counts, lot size and year built, and make sure any updates or renovations you mention in the listing are described accurately, including approximately when they were done. A precise listing supports a smoother appraisal for your seller and better comparable data for every appraisal that uses your sale down the road.
What should I ask the bank/lender?
Ask whether the lending company has begun incorporating the new appraisal reporting system, and, if not, when they will.
Have their underwriters been trained on the new appraisal report? The lender or its appraisal management company must submit the report through the GSEs’ portal correctly, and underwriters need to be ready to review the new format and its findings.
You can also find more information about appraisal changes at NAR.Realtor.
Topics
Member Discussion
Daily Emails
You’ll be the first to know about real estate trends and various legal happenings. Stay up-to-date by subscribing to JustListed.
